
Macro Linkages
A Quarterly Tracking Framework for Semi Buyback Scale and FCF Yield
Semiconductor stocks sit at the intersection of two moving targets: who is buying them, and what their cash flows are worth in a changing macro environment. In one quarter, large institutions dominate flows and free cash flow (FCF) yields look attractive versus bond yields. In another, retail flows surge, multiples expand, and FCF yields compress as rates rise. If you want to understand where you are in the cycle—not just price, but positioning and valuation—you need a framework that connects buyer scale and FCF yield to the macro levers of interest rates, exchange rates, credit, and commodities.
Quantifying the Seesaw Effect Between DXY and Asian Semiconductor Exports
The global chip trade lives on a currency axis. On one side sits the U.S. dollar, measured by the DXY index; on the other side sit Asia’s semiconductor exporters—Korea, Taiwan, Singapore, Malaysia, and others—selling integrated circuits, memory, and logic chips into a world that mostly pays in dollars. When the dollar strengthens, something usually gives. When it weakens, something else usually accelerates. The pattern has become familiar enough that people talk about a “seesaw” between DXY and Asian semiconductor exports.
Synchronicity Regression Test Between Global Manufacturing PMI and Semi Orders
Semiconductors are the nervous system of modern manufacturing. Whether it’s automobiles, industrial machinery, consumer electronics, or data center infrastructure, semi orders reflect what global factories think about the future. At the same time, global manufacturing PMI (Purchasing Managers’ Index) is one of the most watched barometers of industrial health. It’s natural to ask: how synchronized are these two measures? Do manufacturing PMIs and semi orders move together, or do they diverge in ways that matter for investors and policymakers?
The Inverse Relationship Between Mutual Funds’ Overweight Ratio in Semis and Forward Returns
Every cycle has its darlings. In recent years, semiconductor stocks have often played that role, riding the wave of digitization, cloud computing, artificial intelligence, and the endless need for more processing power. Mutual funds, hungry for performance and eager not to miss the next big thing, frequently pile into semis, pushing their portfolio weights well above benchmark levels. Yet a recurring pattern tends to show up: when mutual funds collectively become heavily overweight in semiconductor names, the sector’s forward returns often disappoint.
The Chain Reaction of BOJ Rate Hikes on Yen Financing Costs for Equipment Giants
For decades, Japan’s big equipment makers—tool builders for chips, industrial robots, precision machinery—operated in a world where money in yen was effectively free. Zero or negative rates turned local borrowing into a quiet structural advantage. That world is changing. As the Bank of Japan (BOJ) lifts rates off the floor, the entire chain of yen financing costs moves: from short‑term loans and corporate bonds to global carry trades, FX, and commodity exposures. For equipment giants, this isn’t a footnote. It’s a rewiring of their financial environment.
5-Year Rolling Beta Trends of the Semi Sector vs. Nasdaq 100
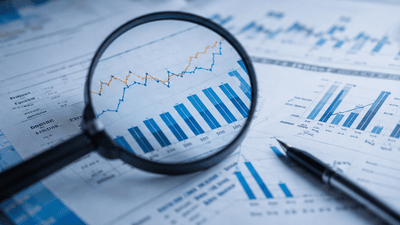
Semiconductors and the Nasdaq 100 have grown up together in the public imagination as the heartbeat of modern technology markets. But inside a portfolio, they are not the same thing. One is a concentrated, cyclical slice of the tech hardware stack; the other is a diversified basket of mega-cap growth, platforms, software, and chips. Over time, the way the semi sector moves relative to the Nasdaq 100—its beta—has shifted with macro regimes, interest rate cycles, credit conditions, and commodity dynamics. Understanding those 5‑year rolling beta trends can turn a macro curiosity into a practical risk tool.
Asymmetric Semi-Crude Correlation: Upside vs. Downside Subsample Analysis
Semiconductor equities rarely move in isolation. Their returns are entangled with macro variables: interest rates, exchange rates, credit spreads, and commodity cycles. Yet the way these linkages show up is not symmetrical. When semis rally, their correlation with macro drivers looks different than when they sell off. Upside and downside markets carry different stories about how the sector interacts with financial conditions. An asymmetric correlation lens—separating upside and downside subsamples—helps uncover those differences.
Quarterly Changes in Global Systemically Important Banks’ Credit Policies for Semis
Semiconductors have moved from a niche industry to the backbone of the global economy. Chips power everything from smartphones and cars to data centers and industrial robots. Behind that impressive hardware, however, sits a quieter but equally important structure: the flow of credit that finances fabs, equipment, inventory, and research. At the center of this structure are Global Systemically Important Banks (G-SIBs), whose quarterly changes in credit policies can subtly, and sometimes not so subtly, reshape the semiconductor landscape.
The Historical High Overlap of Global M2 Growth Inflection and Semi Cycle Bottoms
Semiconductors live in a world of wafers and nodes, but their cycles are written in liquidity as much as in silicon. Over the past few decades, chip busts and booms have tracked not just demand for phones or servers, but swings in global money supply. One of the more intriguing patterns macro investors like to point to is the high overlap between turning points in global M2 growth and bottoms in the semiconductor cycle. When broad money growth stops falling and starts to turn up—“growth reflection”—semi sales and valuations often find their floor not long afterwards.
Historical Performance and Coping Strategies of Semis Under "Stagflation" Scenarios
Stagflation—an uncomfortable mix of persistent inflation and sluggish growth—is the kind of macro regime that makes almost every asset class nervous. For semiconductors, it’s especially tricky. The sector thrives on strong end demand, predictable capex, and manageable input costs. Stagflation undermines all three at once: rates stay high, consumer and industrial demand soften, and commodities can bite margins. Yet semis are not doomed in such environments. History suggests they navigate stagflation with a mix of pricing power, capital discipline, and strategic repositioning.